 Rbia Eman
Independent Financial Habits That Actually Change Your Life
It’s the 22nd of the month, and your wallet is already almost empty. You’re doing the math in your head, wondering where it all went, and thinking about asking someone for a little help until the next salary or allowance arrives.
If that feels familiar, you’re not alone. A lot of young people want an independent financial life, but nobody ever sat them down and explained how to build one. School teaches us algebra and history, but hardly anything about budgeting, saving or handling debt.
Here’s the good news. You don’t need a huge income to get started. What you need is a handful of small, steady habits. Let’s go through them one by one.
What Does an Independent Financial Life Really Mean?
It doesn’t mean being rich. It means having control.When you’re independent financially, you can cover your everyday needs on your own. You have some savings for surprises. And you make money decisions calmly, without panic or pressure from anyone else.
Many people believe they must earn a big salary first. Others think saving is something only older people worry about. Neither is true. Someone with a modest income and good habits can be in a far stronger position than someone who earns more but spends everything.
Why It’s Smart to Start Early
Time is your biggest advantage. Even small amounts set aside regularly can grow into something meaningful over the years, and the earlier you begin, the less you have to sacrifice later.
There’s a mental side to it too. Money stress is heavy. It affects your sleep, your mood and your relationships. When you know you have a cushion and a plan, you feel lighter and more confident about your choices.
And habits stick. What you practise in your teens and twenties often follows you for life, for better or worse. So it’s worth practising the good ones.
8 Independent Financial Habits That Actually Work
1. Track Where Your Money Goes
You can’t fix what you can’t see. For the next 30 days, write down every single thing you spend, even the small stuff. Use a notebook or the notes app on your phone, whatever you’ll actually stick with.
Most people are shocked at the end of the month. That daily snack, the app subscription you forgot about, the little online orders. They look harmless one at a time, but together they can eat up a big chunk of your money.
2. Make a Budget You Can Really Follow
A budget isn’t a punishment. It’s just a plan for your money, so it doesn’t disappear without you noticing.
Keep it simple. Split your income into three buckets: needs (food, transport, bills), wants (fun, shopping, eating out) and savings. There’s no perfect ratio for everyone, so adjust it to your situation. The best budget is one that’s realistic enough for you to follow.
3. Pay Yourself First
Most of us save whatever is left at the end of the month. The problem is that usually nothing is left.
Flip it around. The moment your money arrives, move a fixed amount into savings before you spend anything else. It can be small at the start. What matters is the habit, not the number.
4. Build a Small Emergency Fund
Life loves surprises, and they’re rarely cheap. A phone breaks, a family member falls ill, or your income suddenly stops.
Without an emergency fund, you end up borrowing or panicking. Start with a small target, even enough for a couple of weeks of basic expenses. Then slowly grow it until it covers a few months. Keep this money separate so you’re not tempted to touch it for shopping.
5. Think Before You Buy
Impulse buying is one of the biggest silent money-drainers, especially with ads and sales popping up everywhere.
Try the 24-hour rule. If something isn’t a real need, wait a full day before you buy it. If you still want it tomorrow, fine. Very often, the urge disappears by itself. It also helps to ask yourself a simple question: is this a need or a want?
6. Stay Away from Unnecessary Debt
Some debt can be useful, like a loan that helps you study or build a business. But borrowing money just to keep up with other people, or to buy things that lose value quickly, is a trap.
Before you borrow, ask yourself how you’ll pay it back and whether it’s really worth it. If the answer is unclear, wait. Your future self will be grateful.
7. Learn the Basics of Investing
Money that sits idle slowly loses its buying power because prices tend to rise over time. That’s why many people put their savings to work through investing.
You don’t have to become an expert overnight. Start by learning the basics, like what risk means, why spreading your money around is safer, and why starting early helps. Take your time, and never put in money you can’t afford to lose. If you’re unsure, a qualified financial professional can guide you.
8. Build Another Way to Earn
Relying on only one source of income can feel risky. Picking up a skill, freelancing, or doing part-time work gives you a second stream of money and more options.
Even a small extra income helps. It speeds up your savings, and it gives you the confidence that you can always find a way.
A Simple 30 Day Plan to Get Started
Feeling overwhelmed? Take it slow and just focus on one week at a time. In the first week, simply track every expense without judging yourself. In the second week, use what you noticed to create a basic budget and set one clear saving goal.
During the third week, start your emergency fund, even with a tiny amount, and cut one expense you don’t really need.
In the fourth week, look back at how it went, adjust what didn’t work, and learn one new thing about money, like how saving accounts work or how investing basics are explained.
After that month, you’ll have a system that belongs to you. That’s a strong foundation for a truly independent financial life.
Common Money Mistakes Young People Make
Almost everyone makes some of these at the start, so don’t beat yourself up. Just try to spot them early.
- Spending first, saving later. As we said, there’s rarely anything left over.
- Copying other people’s lifestyles. What you see online isn’t the full picture, and you don’t know what they’re paying for it.
- Ignoring small expenses. They quietly add up.
- Waiting for the perfect time. There’s no perfect time. Starting small today beats starting big someday.
- Having no goal. Saving is much easier when you know what you’re saving for.
What Changes When You Stick to These Habits
You won’t see a miracle in a week. But over a few months, the changes are real and noticeable.
You’ll worry less about money because you know where it’s going. You’ll build savings that give you a safety net. You’ll feel more confident when it’s time to make big decisions, like choosing a job, continuing your studies or starting something of your own.
And you’ll have more freedom, since you won’t have to depend on others for every expense.Of course, results depend on your income, your situation and how consistent you are. But the direction is always the same: more control and less stress.
Final Thoughts
Building an independent financial life isn’t about luck or a huge paycheck. It’s about a few small habits repeated over and over: knowing where your money goes, saving before you spend, thinking before you buy, and slowly growing your skills and income.
You don’t have to do everything at once. Pick one habit from this list and start today. Maybe just write down what you spend before you go to bed tonight. That one small step is where a stronger, more independent future begins.
Frequently Asked Questions
How can I become independent financially at a young age?
Start with the basics. Track your spending, make a simple budget, save a little every time money comes in, and avoid unnecessary debt. Small, steady steps matter more than big ones.
How much should I save every month?
There’s no single answer, since it depends on your income and expenses. Many people aim for a portion of their income, and even a small, regular amount is a good start. Increase it as your income grows.
Is it possible to be financially independent with a low income?
Yes. It may take longer, but good habits like budgeting, avoiding waste and saving regularly still make a real difference. Building an extra income source can also help.
What is the first step towards financial independence?
Knowing where your money goes. Track your spending for a month, and everything else becomes easier to plan.
How long does it take to build financial stability?
It varies from person to person. Some people feel a difference in a few months, while for others it takes longer. What matters most is staying consistent.
Everyone fails in life. This isn’t a dark view, it’s just a fact none of us can dodge.Failure itself isn’t the real problem. The real problem is letting failure shape how you see yourself and your future.
This guide explains how to change your view of failure. You will learn real steps to turn setbacks into lasting growth.By the end, you will have a clear plan for using failure as a tool for success, not a reason to quit.
Why Failure Feels So Difficult
Failure carries a real emotional weight. Missed chances, failed relationships, and turned-down efforts can all leave us feeling let down.
Many people let failure eat into their sense of self-worth. This often builds a belief that real success will never happen for them.
The Shift That Changes Everything
Winston Churchill once said that the courage to keep going matters more than any one failure. This idea captures the mindset shift that makes lasting growth possible.
Learning to welcome failure, not fear it, opens the door to real personal growth. This shift doesn’t happen fast, but it is fully possible.
Why We Learn More From Failure Than Success
Failure often teaches lessons that success simply can’t. This idea has been said by thinkers and writers across many years.
What Failure Offers That Success Doesn’t
- A clearer view of your real weak spots
- Real feedback on what isn’t working
- Push to try new ways of doing things
- Deeper strength built through hard times
Success can feel great, but it rarely forces the same level of thought. Failure, on the other hand, often demands it.
The Biggest Mistake People Make With Failure
Many people try to move past failure too fast. They hope things will just get better on their own next time.
Why “Hoping for the Best” Doesn’t Work
Feeling bad about a failed result is a normal reaction. It’s also normal to want to push that feeling away fast.
Learning how to overcome life challenges can help you build resilience, develop a positive mindset, and handle difficult situations with greater confidence.But pushing failure aside with no real look at it rarely brings real change. Without knowing what went wrong, the same pattern often repeats.
A Common Example
Think of a relationship that ends after ongoing fights. It’s easy to blame the other person and assume the next one will just work out better.
Without an honest look at what happened, though, the same patterns often keep going. Real change takes more than hope alone.
Four Key Lessons for Turning Failure Into Success
Learning to grow from failure takes real, focused effort. These four lessons give a clear plan for real, lasting change.
| Lesson | Core Idea |
| Redefine failure | Change what failure means to you inside |
| Take action, don’t just hope | Look closely and adjust after setbacks |
| Find the “why” | Find the true root cause of each failure |
| Take responsibility | Own your response, no matter the cause |
Lesson 1: Adjust Your Definition of Failure
This is both the most key and the hardest step. Before you can learn from failure, you must change what it means to you.
Why Failure Feels So Heavy
If failure leaves you feeling like your goals are out of reach, it’s time to redefine it. Ask yourself, with honesty, why failure truly hurts.
Are you upset about the failure itself? Or are you more worried about what others may think of you?
The Weight of Other People’s Opinions
It’s easy to let failure crush you when you give too much weight to others’ views. Parents, friends, partners, and coworkers can all shape how heavy failure feels.
Remember that everyone fails. Failing today doesn’t make you any less able than someone who fails tomorrow.
Reframing Failure as Opportunity
- Treat failure as a chance to look within
- Use it to reshape what truly matters to you
- Train your mind to spot the lessons inside it
- Use those lessons to move toward what you want
Adjusting your view of failure takes real work. Once you start seeing failure as a step toward success, real change becomes possible.
Lesson 2: Don’t Just Assume Things Will Be Better Next Time
Hope is valuable, but it’s not enough on its own. Turning failure into success takes action, not just hope.
The Trap of Passive Optimism
When we fail, we naturally feel bad about the result. It’s tempting to push that feeling away and assume things will just get better.
Sadly, this passive way rarely brings real change. Without action, the same failures tend to happen again.
Breaking the Cycle
The world won’t fix your failures for you. Only you can find what went wrong and make the needed changes.
This means moving past hope and into honest review. The next lesson shows just how to do this.
Lesson 3: Break Down Exactly What Went Wrong
To truly learn from failure, you need to find the “why” behind it. This is the real reason things didn’t go as planned.
Why Finding the “Why” Is Hard
Looking for the root cause can feel very hard, mainly when feelings run high. It’s okay to let some time pass before you dig into what happened.
Just don’t forget to look once you’re ready. Once feelings settle, go back and give it an honest look.
How to Search for the Root Cause
- Build a timeline of events that led to the failure
- Ask what real lessons can be learned
- Think about if your reactions were fair
- Think about if you could have done something different
- Check if you were focused on the right issues
Questions Worth Asking Yourself
- Was I being unfair in this case?
- Could I have done something different?
- Was I focused on the right issues?
The exact questions matter less than the habit of asking them. Looking back with honesty is what builds real learning.
When the Cause Feels Out of Your Control
At times failure seems caused by someone else or by things past your control. This is rarely the full story.
In these cases, focus on how you respond to it. Your response becomes the “why” you can truly learn from.
Lesson 4: Take Responsibility for Your Failures
Whether a failure came from your own acts or from outside factors, owning your response matters most.
The Trap of Blame
Blaming a failure on someone or something else often feels like the easy road. This path carries a real cost, though.
Staying stuck in a victim mindset makes it near impossible to take charge of your growth. It keeps you stuck, waiting for things to change instead of changing yourself.
Why Responsibility Creates Power
Your happiness and how you respond to life’s tests stay your own job. This idea has been echoed by many successful people across many fields.
When you own failed cases, no matter the cause, you gain real power over your future choices. This shift changes everything about how failure feels.
What Happens When You Adopt This Mindset
- Failure starts to feel less scary over time
- You start looking for lessons instead of avoiding them
- Each setback moves you closer to your real goals
- Confidence builds through steady, honest thought
Practical Strategies for Applying These Lessons
Knowing these four lessons is one thing. Using them often is what brings real, lasting change.
Daily Habits That Support Growth From Failure
- Think back briefly on setbacks instead of ignoring them
- Write down clear lessons learned from each failure
- Set small, doable goals based on those lessons
- Track patterns across many failures over time
Building a Personal Failure Review System
- Pause before you react with emotion to a setback
- Give yourself time to work through the first feelings
- Come back later and give an honest look at what happened
- Find one or two clear lessons to use
- Take one real action based on those lessons
This clear plan turns failure from a source of shame into a real tool for growth.
How This Mindset Shift Changes Long-Term Success
Using these lessons doesn’t just help with single setbacks. It fully changes how you face challenges over time.
Long-Term Benefits of This Mindset
| Benefit | Impact Over Time |
| Less fear of failure | More willing to take risks |
| Faster bounce-back from setbacks | Less time stuck feeling down |
| Clearer self-awareness | Better choices in future cases |
| Stronger inner strength | Better able to face future challenges |
These gains build up over time. Each failure handled well makes the next one easier to face.
Common Obstacles to Learning From Failure
Even with the right mindset, some blocks can get in the way. Spotting these early helps you work through them with more ease.
Common Obstacles to Watch For
- Letting shame block honest self-review
- Rushing past feelings instead of working through them
- Blaming outside things with no look at your own part
- Repeating the same patterns with no real change
- Comparing your failures to someone else’s seeming success
Knowing these blocks doesn’t remove them fully. Still, spotting them makes it easier to work through them when they show up.
Why Self-Compassion Matters in This Process
Owning your failures doesn’t mean being hard on yourself. Self-kindness plays a real part in growth that lasts.
Balancing Responsibility With Self-Compassion
- Own mistakes with no harsh self-blame
- Treat yourself with the same care you’d give a friend
- Notice effort, not just results
- Give yourself time to work through hard feelings first
This balance stops the process from turning into more self-punishment. Growth works best when it comes from real self-respect.
Final Thoughts on Turning Failure Into Success
Life will always bring both ups and downs. Some of those downs will truly hurt, and that’s a normal part of being human.
What matters most isn’t dodging failure fully, since that’s just not possible. What matters is how you choose to respond when failure hits.
You can let failures weigh you down, or you can own them, learn from them, and keep pushing toward your goals. That choice stays fully yours.
Frequently asked questions
Why Is It Important to Redefine Failure?
Redefining failure helps lift the emotional weight that often comes with it. This shift makes it easier to see failure as a lesson, not a defeat.
How Do I Find the Real Reason Behind a Failure?
Build a timeline of events and ask honest questions about your own part in it. Give yourself time to work through feelings before you review what happened.
What If My Failure Was Someone Else’s Fault?
Even when outside things play a part in failure, focus on how you respond to it. Your response becomes the lesson you can truly control and learn from.
Why Does Taking Responsibility Matter So Much?
Taking responsibility moves you out of a victim mindset and into a place of power. This makes it possible to truly learn and grow from setbacks.
How Long Does It Take to Change My Relationship With Failure?
This mindset shift takes time and steady practice. Most people see slow, real growth as they use these lessons again and again over months.
Can Failure Really Lead to Success?
Yes, failure often gives lessons that success can’t. Many successful people point to certain failures as turning points in their growth.
What’s the Difference Between Self-Blame and Taking Responsibility?
Self-blame means harsh self-judgment with no real gain. Taking responsibility means giving your part in it an honest look and using that to grow.
How Do I Stop Repeating the Same Failures?
Finding the true “why” behind each failure and making clear changes helps break repeating patterns. Tracking these patterns over time also shows useful clues.
The Night I Realised Something Had to Change
It was 2 a.m., and I was scrolling through my phone for the third hour in a row. My eyes were burning, my back ached, and I felt exhausted even though I had done nothing all day.
That was the night I admitted it: I was tired all the time, I got out of breath climbing one flight of stairs, and every I’ll start Monday promise had quietly died by Wednesday.
I had tried everything the internet told me to try. Extreme workout challenges. Two-hour gym plans. Copying routines from people who looked nothing like me and lived nothing like my life. Each time, I quit within two weeks and felt worse than before.
What I didn’t know then is that the problem was never me. I was following someone else’s plan. What I needed was a personal exercise programme, one built around my schedule, my energy and my goals.
Why Most Young People Quit Their Workouts
If you have ever started strong and disappeared after ten days, you are in very good company. Most of us fail for the same few reasons:
- The plan is too big. An hour a day, seven days a week, is a recipe for burnout.
- The plan is copied. A routine that suits a fitness influencer may not fit your classes, job or sleep cycle.
- There is no clear reason. Without a reason that matters to you, motivation fades the moment life gets busy.
- Progress is invisible. When you can’t see change, it feels pointless.
A personal exercise programme solves all four, because it starts with you, not with a trend.
Why You Need a Personal Exercise Programme (Even If You Feel Fine)
Most of us spend our days sitting: in class, at a desk, on the bed with a phone. It doesn’t feel dangerous because the effects are slow and quiet. But over time, they add up.
- About 1 in 4 adults and roughly 8 in 10 teenagers worldwide do not get enough physical activity.
- Young people aged 5 to 17 are advised to get an average of 60 minutes of moderate to vigorous activity a day, while adults are advised to get 150 minutes or more per week.
- People who are not active enough have a noticeably higher risk of heart disease, type 2 diabetes and early death compared with people who move regularly.
The good news is that you don’t need a complicated fix. You need a plan that fits your life.
Does this sound like you?
- You feel tired even after sleeping enough.
- You lose focus halfway through studying or working.
- You get stressed or irritable more easily than before.
- You get out of breath doing simple things.
- You keep saying “I’ll start tomorrow.”
If you nodded at even two of these, this article is for you.
How I Built My Personal Exercise Programme in 5 Simple Steps
Step 1: Find Your Real “Why”
I sat down with a notebook and asked myself one question: what do I actually want? Not “a perfect body”. I wrote: more energy, better sleep, and to stop feeling tired by 4 p.m.
That was specific and emotional, and it became the reason I got out of bed on lazy mornings. Write yours down and keep it where you can see it.
Step 2: Start Ridiculously Small
My first week was just 10 minutes a day: a short walk, a few stretches, some bodyweight squats. It felt almost silly, but that was the point. I wasn’t trying to get fit in a week. I was trying to become someone who exercises.
Step 3: Balance Three Types of Movement
After two weeks, I built my routine around three pillars:
- Cardio (walking, cycling, skipping rope) for heart health and stamina
- Strength (push-ups, squats, planks, resistance bands) for muscles, posture and bones
- Mobility (stretching, yoga-style flows) for flexibility and fewer aches
You don’t need a gym or expensive equipment. Your living room and a mat are enough.
Step 4: Schedule It Like a Meeting
I stopped asking do I feel like exercising today? because the answer was often no. Instead, I picked fixed slots and treated them like appointments I couldn’t cancel.
Step 5: Track, Celebrate and Adjust
Every Sunday, I noted three things: what I did, how I felt and what I’d change. Some weeks I hit every workout, some weeks only two. Both counted. A flexible plan survives real life, and that is what makes it work.
A Simple Weekly Plan You Can Copy and Customise
| Day | Activity | Time |
| Monday | Brisk walk + light stretching | 20 min |
| Tuesday | Bodyweight strength (squats, push-ups, plank) | 20 min |
| Wednesday | Rest or gentle stretching | 10 min |
| Thursday | Cardio (cycling, skipping or dancing) | 25 min |
| Friday | Bodyweight strength + core | 20 min |
| Saturday | Fun activity (sports, hiking, swimming) | 30 min |
| Sunday | Rest and weekly review | — |
Adjust the days and durations to fit your life. This is a starting point, not a rulebook.
What Happens When You Follow Your Plan: A Realistic Timeline
Results don’t arrive overnight, but they do arrive. Everyone’s body is different, so treat this as a guide, not a guarantee. In the first two weeks, you may feel some soreness, but you will likely notice slightly better sleep and a quiet pride in simply showing up.
By weeks three and four, daytime energy usually improves, the afternoon tiredness starts fading, and your workouts begin to feel easier. Around weeks six to eight, you may notice better stamina and strength, improved posture and a calmer mind under pressure.
By weeks eight to twelve, changes in your fitness and body shape often become visible, and your confidence grows with them. After six months and beyond, exercise stops feeling like a task and becomes part of who you are, with lasting energy and stronger discipline that spills into other areas of life.
One study on habit-building found that a new behaviour takes about two months on average to feel automatic, though it varies from person to person. So if the first weeks feel hard, that is completely normal. You are not failing. You are still building.
The Benefits I Noticed and How They Can Help You Too
Around week four, I noticed things I hadn’t expected. Here is what changed, and why it may change for you as well:
- More energy, not less. The 4 p.m. crash faded. Moving more usually leaves you with more energy, not less.
- Sharper focus. Regular movement supports blood flow to the brain, which many people find helps concentration and memory during study or work.
- A calmer mind. Physical activity is widely linked to lower stress and anxiety, and it helps your body release feel-good chemicals.
- Deeper sleep. I fell asleep faster and woke up more refreshed, which is a common result of regular exercise.
- A stronger body and better posture. Strength work protects your back, joints and bones, especially if you sit for long hours.
- Higher confidence. Every workout you finish is a promise you kept to yourself, and that builds real self-belief.
- Long-term health protection. The habits you build in your teens and twenties can lower your risk of many lifestyle-related health problems later on.
The recommended 150 minutes per week works out to roughly 20 to 25 minutes a day, which is less time than one episode of your favourite show.
Mistakes to Avoid
- Skipping the warm up. Five minutes prevents a lot of injuries.
- Comparing yourself to others. Your only competition is who you were last week.
- Ignoring rest days. Muscles recover and grow when you rest, not while you train.
- Chasing perfection. Missing one day doesn’t ruin the plan. Quitting after it does.
What Happens If You Keep Delaying?
This isn’t about fear, just honesty. If nothing changes, the tired feeling, low motivation and stiff body usually don’t disappear on their own. They tend to become your normal. The best time to start is when the change is still small and easy. Ten minutes today is far easier than an overhaul a year from now.
Quick Self-Check: Are You Ready to Start?
- Can I spare 10 to 20 minutes a day?
- Do I have a clear reason (energy, confidence, focus, health)?
- Am I willing to start small and be patient?
If the answer is yes to all three, you already have everything you need.
Frequently Asked Questions
How long does it take to see results from a personal exercise programme?
Most people notice better energy and mood within two to four weeks. Visible physical changes usually take eight to twelve weeks, depending on consistency, nutrition and sleep.
Do I need a gym membership?
No. Bodyweight exercises, walking, skipping and simple resistance bands are enough for a strong beginner programme.
What if I miss a few days?
Restart with your next scheduled session. Consistency over months matters far more than perfection in a single week.
How many days a week should a beginner exercise?
Three to five days is a great range. Begin with three and increase gradually as your body adapts.
Leave a Reply
Every growing business needs clear direction for its money decisions. Financial planning and analysis, or FP&A, provides exactly that direction. This guide explains everything you need to know about FP&A.
You will learn what FP&A actually does day to day. You will also learn how it differs from traditional accounting. By the end, you will understand why FP&A matters so much.
What Is Financial Planning and Analysis?
Financial planning and analysis is the forward looking side of finance. It focuses on budgeting, forecasting, and strategic planning activities. FP&A teams analyze data to guide smart business growth.
Core Definition and Purpose of FP&A
FP&A is a set of strategic activities supporting financial health. These activities include planning, budgeting, forecasting, and detailed analysis. Together, they help companies grow profitably and sustainably.
The purpose is simple: connect financial data to business strategy. FP&A tells business leaders where they stand financially. It also shows them where they’re headed next.
How FP&A Fits Into the Finance Function
Finance departments handle many different responsibilities across an organization. FP&A represents the analytical, forward-thinking piece of this puzzle. It works alongside accounting, treasury, and other finance teams.
While other teams record and manage money, FP&A predicts outcomes. This predictive role makes FP&A essential for strategic decision-making. Business leaders rely heavily on FP&A insights daily.
FP&A vs Accounting: Key Differences
Many people confuse FP&A with traditional accounting work. Understanding the difference clarifies why both functions matter separately.
Backward-Looking vs Forward-Looking Focus
Accounting focuses on recording what already happened financially. This includes tracking transactions and ensuring regulatory compliance. Accountants produce standardized financial statements from historical data.
FP&A instead asks what will happen in the future. This forward-looking perspective requires different analytical skills entirely. Scenario modeling and trend analysis become essential tools here.
| Aspect | Accounting | FP&A |
| Time focus | Historical (past) | Forward-looking (future) |
| Main goal | Compliance and accuracy | Strategic decision support |
| Key outputs | Financial statements | Forecasts and models |
| Core question | What happened? | What will happen next? |
Roles and Responsibilities Compared
Accountants ensure every transaction gets recorded correctly and legally. FP&A analysts instead build models predicting future company performance. Both roles require strong financial knowledge and attention to detail.
FP&A professionals often work closely with department heads too. This collaboration helps create realistic, achievable financial targets together.
Core Functions of FP&A
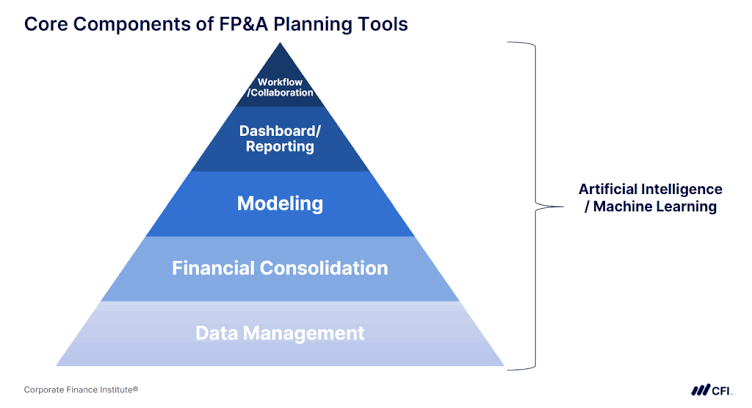
FP&A covers several distinct but interconnected financial activities. Each function plays a unique role in business strategy.
Budgeting and Annual Planning
Annual budgeting sets financial targets for the entire organization. This process involves collaborating with every department head individually. Together, they create realistic revenue and expense projections.
Budgets become the North Star guiding operations all year. Every department aligns its spending against these agreed targets.
Financial Forecasting
Forecasting updates predictions as new information becomes available regularly. Rolling forecasts adapt continuously to changing business conditions. This flexibility helps companies respond quickly to market shifts.
Common forecasting elements include:
- Revenue projections based on sales trends
- Cash flow predictions for liquidity planning
- Expense forecasts across all departments
- Headcount and hiring plan projections
Financial Modeling
Financial models turn business data into mathematical representations. These models help analysts test different business scenarios objectively. The right model depends entirely on what’s being predicted.
Analysts use these models to build various financial projections. This includes revenue forecasts, cash flow estimates, and expense predictions.
Variance Analysis and Performance Management
Variance analysis compares actual results against original budget predictions. This comparison reveals where performance exceeded or missed expectations. Understanding these gaps helps teams adjust future strategies.
Performance management uses this data to track ongoing company health. Regular reviews keep everyone accountable to financial goals.
Strategic Planning and Scenario Analysis
Strategic planning connects financial data to long-term business goals. FP&A teams model different scenarios to prepare for uncertainty. This includes best-case, worst-case, and most-likely projections.
Scenario planning proves especially valuable during unpredictable economic periods. It helps leadership make informed decisions despite uncertainty.
The FP&A Process Explained
Understanding the FP&A workflow helps clarify how insights get generated. This process follows several distinct, connected stages.
Data Collection and Consolidation
Everything starts with gathering data from across the organization. This includes financial records, operational metrics, and market information. Consolidating this data creates a complete company picture.
Data silos often complicate this collection process significantly. Modern FP&A teams work to break down these barriers.
Analysis and Assumption Building
After collecting data, analysts make assumptions about future performance. These assumptions consider company goals like revenue growth or cost reduction. Financial models translate these assumptions into concrete numbers.
This analytical stage requires both technical skill and business judgment. Analysts must balance optimism with realistic expectations.
Reporting to Leadership and the Board
Final insights get compiled into clear, actionable reports. These reports go to the CFO, CEO, and board members. Public companies also face additional regulatory reporting requirements.
Annual forecasts typically include specific budget recommendations too. These recommendations guide department operations throughout the year.
Why FP&A Matters for Business Growth
FP&A isn’t just a back-office function anymore. It has become a genuine strategic partner to the business.
Supporting CFO and Executive Decisions
FP&A provides the analytical foundation for major executive decisions. CFOs rely on FP&A insights for strategic planning constantly. Without this support, decisions would rely on guesswork alone.
The CFO role has evolved significantly over recent years. FP&A now helps CFOs become true business partners.
Risk Mitigation Through Forecasting
Accurate forecasting helps identify potential risks before they escalate. This early warning system protects company resources proactively. Management can take preventive action based on these insights.
Missing a forecast can seriously damage investor and stakeholder confidence. Strong FP&A practices help companies avoid this costly mistake.
Optimizing Resource Allocation
FP&A ensures money gets allocated where it creates the most value. Detailed analysis prevents wasteful spending across departments. This optimization maximizes return on every dollar invested.
Resource optimization also means correctly funding growth opportunities. FP&A identifies which initiatives deserve additional investment.
Common Challenges in FP&A
Despite its importance, FP&A teams face real operational obstacles. Recognizing these challenges helps organizations address them proactively.
Data Silos and Fragmented Tech Stacks
Many companies struggle with data scattered across different systems. This fragmentation makes consolidation slow and error-prone. Nearly 87% of finance leaders say their FP&A needs improvement.
Breaking down these silos requires better technology integration. Connected systems allow for faster, more accurate analysis.
Keeping Pace With Business Change
Business conditions change faster than traditional FP&A processes sometimes. Annual budgets can become outdated within just a few months. This lag creates a gap between planning and reality.
Rolling forecasts help address this challenge more effectively. They allow continuous adjustment rather than rigid annual planning.
Tools and Technology Used in FP&A
Modern FP&A relies heavily on specialized software and platforms. These tools transform raw data into actionable business insights.
Financial Modeling Software
Dedicated FP&A platforms replace outdated spreadsheet-based processes increasingly. These tools offer better accuracy and collaboration features. They also integrate directly with other business systems.
Popular platform categories include:
- Integrated planning and budgeting software
- Cash flow and forecasting tools
- Scenario modeling applications
- Reporting and dashboard platforms
Automation and AI in Modern FP&A
Artificial intelligence increasingly supports FP&A forecasting and analysis work. Automation reduces time spent on manual data processing. This shift lets analysts focus more on strategic thinking.
Companies using these tools report spending more time analyzing. Meanwhile, less time gets wasted on basic data processing.
Careers in Financial Planning & Analysis
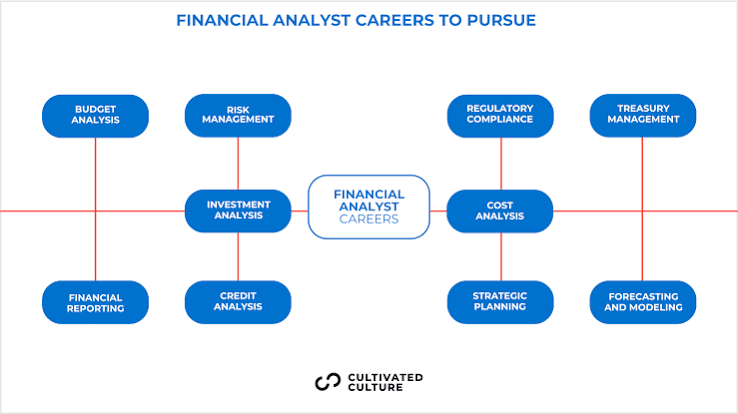
FP&A offers strong career opportunities for finance professionals. Growing demand makes this an attractive career path currently.
Common FP&A Job Roles
FP&A teams include several specialized positions at different levels. Entry-level analysts typically handle data collection and basic reporting. Senior roles focus more on strategy and leadership.
Typical FP&A career titles include:
- Financial Analyst
- Senior FP&A Analyst
- FP&A Manager
- Director of FP&A
- VP of Financial Planning and Analysis
Skills Needed for an FP&A Career
Successful FP&A professionals combine technical and interpersonal skills. Strong Excel and modeling abilities remain essential foundational skills. Communication skills matter equally for presenting insights clearly.
Key skills for FP&A success include:
- Financial modeling and forecasting expertise
- Data analysis and interpretation abilities
- Clear business communication skills
- Strategic thinking and problem-solving
- Familiarity with FP&A software platforms
FP&A Certifications
Professional certifications can strengthen your FP&A career significantly. These credentials demonstrate expertise to potential employers. They also often lead to better job opportunities.
Recognized certifications include the Certified Corporate FP&A Professional designation. This certification validates specialized planning and analysis knowledge.
Frequently Asked Questions About FP&A
What does FP&A stand for?
FP&A stands for Financial Planning and Analysis. It’s the forward-looking finance function focused on budgeting and forecasting.
Is FP&A the same as accounting?
No, accounting records historical transactions and ensures compliance. FP&A instead focuses on future predictions and strategic planning.
What skills are needed for an FP&A career?
Strong financial modeling, data analysis, and communication skills matter most. Familiarity with FP&A software also helps significantly.
Why is FP&A important for businesses?
FP&A connects financial data to strategy, guiding smarter business decisions. It also helps mitigate risk through accurate forecasting.
What tools do FP&A teams use?
FP&A teams use modeling software, forecasting tools, and reporting platforms. Many now incorporate automation and AI capabilities too.
Leave a Reply
Owning a rental flat isn’t the only path to earning from property. If you’re wondering how to build passive income with real estate without chasing tenants or fixing leaky taps, there are several routes that let your money work in the property market while you stay hands off.
This guide breaks down five practical strategies, how much capital each one needs, and what risks to watch out for before you invest.
What Does Passive Real Estate Income Actually Mean?
Passive real estate income is money you earn from property-related investments without managing the property yourself. Buying a house and dealing with tenants directly is active investing. Buying units in a fund where professionals manage the properties for you is passive investing.
That said, passive doesn’t mean effortless.You still need to research each option, understand the fees involved, and check in on your investment now and then. The real advantage isn’t zero work, it’s far less ongoing work.
5 Ways to Build Passive Income with Real Estate
Here’s how to build passive income with real estate without purchasing a whole property outright.
1. Real Estate Investment Trusts (REITs)
REITs are one of the simplest entry points into property investing. A REIT owns or finances a portfolio of income-generating buildings, think office spaces, malls, or warehouses. When you buy units, you earn a share of the rental income through periodic payouts, and your investment can also grow in value over time.
The biggest perk is liquidity. Since REIT units trade on the stock market, you can buy or sell them fairly easily, unlike physical property, which can take months to sell. The trade-off is that unit prices move up and down with the market, and you have no say in how the underlying properties are run.
2. Property Focused Investment Funds
Another option is investing in funds that hold shares of companies connected to the real estate sector construction firms, property developers, or infrastructure businesses. These funds give you indirect exposure to the industry without owning any physical asset.
Before investing, check exactly what the fund holds. A fund tied to real estate-linked companies is not the same as owning a building or collecting rent directly. You can typically access these through your regular brokerage or mutual fund platform.
3. Fractional Real Estate Ownership
Fractional ownership lets several investors jointly own one property instead of one buyer covering the entire cost. This opens the door to higher-value properties that would otherwise be out of reach for an individual investor.
Depending on how the deal is structured, you may earn a share of the rental income and benefit if the property’s value rises. Before committing money, ask:
- How is ownership legally documented?
- Who manages the property day to day?
- What fees will you pay?
- How and when can you exit the investment?
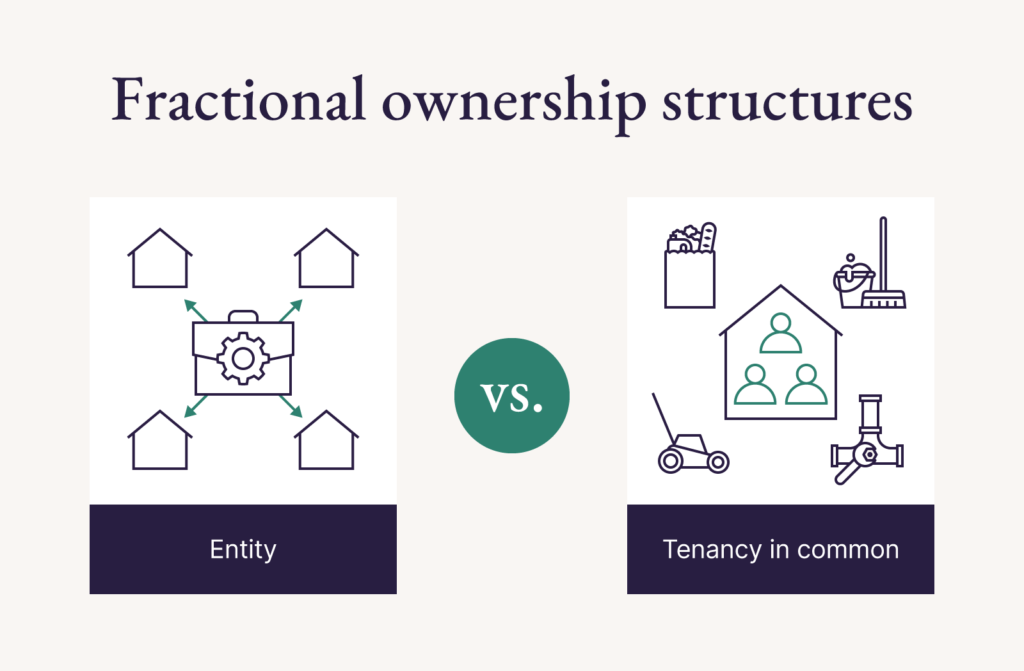
Some regulated structures set a fairly high minimum investment, while smaller private platforms allow much lower entry amounts by pooling investors into a shared legal entity that holds the property.
Keep in mind that fractional investments are usually far less liquid than listed options like REITs, so your money could stay locked in for longer than expected.
4. Real Estate Crowdfunding and Pooled Investments
Crowdfunding lets a group of investors fund a property project together instead of one person financing it alone. Rather than putting up the entire amount yourself, you contribute a portion alongside others.
This route calls for careful homework. Look closely at the platform’s track record, the developer behind the project, the legal structure of the deal, expected cash flows, and how you’ll eventually get your money back.
Never invest purely because a project promises an eye-catching return dig into the fine print first. Many of these opportunities are aimed at investors with a higher capital threshold, so check the minimum ticket size before you get interested.
5. Real Estate Syndication
Syndication works similarly to crowdfunding but is usually more structured. A group of investors pools money into a single property deal, and a sponsor or professional manager runs the project on their behalf. Investors typically act as passive partners, contributing capital while the sponsor makes the operational decisions.
This can open doors to large-scale projects that would be impossible to fund alone. The downside is a long holding period, limited liquidity, and less control over major decisions. Before signing on, review the legal documents, fee structure, and how profits (and losses) are shared.
How Much Money Do You Need to Get Started?
There’s no fixed number here the amount depends entirely on which route you choose. Listed REITs generally require far less capital than buying a flat or commercial unit outright. Fractional ownership and pooled investments can also lower the entry barrier, though minimums vary widely by platform and project.
Buying a rental property directly is the most capital-intensive option once you factor in the purchase price, registration costs, financing charges, and ongoing maintenance.
Instead of asking What’s the smallest amount I can invest?, ask yourself: “How much can I invest without putting my day-to-day finances at risk?”
Which Passive Real Estate Strategy Fits You Best?
| If you value | Consider |
| Easy buying and selling | Listed REITs |
| Full ownership | A rental property with professional management |
| Minimal day-to-day involvement | REITs or managed investment funds |
| Access to large-scale projects | Syndication |
| Shared ownership of one asset | Fractional ownership structures |
| Steady, property-linked income | REITs or a rental property |
This is a general starting framework, not personal financial advice — your choice should depend on your own goals and risk appetite.
Risks Worth Knowing Before You Invest
Passive doesn’t mean risk-free. Keep these points in mind:
- Property values can decline.
- Rental units can sit vacant for stretches of time.
- Rising interest rates can push up borrowing costs.
- Private or fractional investments can be hard to exit quickly.
- Management issues, regulatory shifts, hidden fees, and unexpected expenses can all eat into your returns.
With pooled or fractional deals specifically, your outcome also depends on the platform or sponsor managing the project. Always understand where your money is going and how you’ll get it back before investing.
How to Start Building Passive Income Through Real Estate
- Set your goal. Decide if you want regular income, long-term growth, or a mix of both.
- Review your finances. Know your income, expenses, and how much you can realistically set aside.
- Pick your comfort level. Choose between a fully hands-off approach or something closer to managed ownership.
- Research thoroughly. Study the property, the people managing it, the fee structure, and the risks involved.
- Understand your exit. Know exactly how and when you can withdraw or sell your investment.
- Invest responsibly. Avoid using money you might need in the near term.
- Review regularly. Passive investing still needs periodic check-ins.
In Summary
If you’re figuring out how to build passive income with real estate, you don’t need to buy a flat or take on tenants to get started. REITs, property-focused funds, fractional ownership, crowdfunding, and syndication all offer different levels of involvement, capital requirements, and risk. The right one for you depends on how much liquidity, control, and involvement you’re comfortable with so start small, research thoroughly, and build from there.
Frequently Asked Questions
Is passive real estate income truly passive?
Not completely. You’ll still need to research the opportunity, review documents, and monitor performance occasionally. It reduces ongoing effort and doesn’t eliminate it.
What’s the easiest way to start earning passive income from real estate?
For most beginners, listed REITs are the simplest starting point because of their lower entry cost and easy liquidity compared to physical property.
Can I lose money with passive real estate investments?
Yes. Property values can fall, rental income can dip, and pooled investments carry additional risk tied to the platform or sponsor managing the deal.
How is fractional ownership different from a REIT?
A REIT pools money from many investors into a diversified portfolio of properties and trades like a stock. Fractional ownership usually ties your money to one specific property, with lower liquidity and a more defined exit process.
How much capital do I need to begin?
It depends on the route. REITs generally need the least capital, while direct property purchase and select crowdfunding deals require significantly more.
Leave a Reply
There’s no single hairline shape that counts as “normal.” Hairlines look different from person to person, and that’s fully natural.
Some hairlines sit low, others sit high. Some have a widow’s peak or a cowlick, and all of these are fully normal.
This guide explains the different types of hairlines, how receding hairlines happen, and what treatment options exist. You will also learn styling tips and when to see a doctor.
By the end, you will get your own hairline better and know your options if you want a change.
Understanding What a Normal Hairline Looks Like
A hairline is simply the spot where hair grows out from the scalp. Its exact shape can differ a lot from person to person.
As people age, hairlines often shift, mainly in men. This shift is usually slow and may not be clear to others right away.
Patterned Hair Loss Affects Both Sexes
Both men and women can face patterned hair loss. Research shows this is the most common type of hair loss for both sexes.
Knowing this helps make sense of something many people worry about alone. Hairline changes are a shared human trait, not a rare issue.
Types of Normal Hairlines
Hairlines come in a few clear shapes. Knowing each type helps you spot your own hairline and how it might shift over time.
| Hairline Type | Key Feature |
| Low hairline | Sits close to the eyebrows |
| Middle hairline | Sits toward the upper middle of the forehead |
| High hairline | Begins at the crown of the head |
| Straight-lined | Forms a straight line with 90-degree side angles |
| Bell-shaped | Forms an upside-down U-shape |
| Triangular | Angular shape rising to a point in the center |
| Uneven | One side sits higher than the other |
| Cowlick | A small swirl growing in a different direction |
Low Hairline
A low hairline sits closer to the eyebrows than other types. This can make the face and forehead look smaller.
Low hairlines look fairly alike between men and women. They may also stand out less if they recede, since less scalp shows.
Middle Hairline
A middle hairline is often what people think of as a “normal” hairline. It sits toward the upper middle part of the forehead.
With this type, hair often recedes more at the sides. This makes the well-known M-shape many people know.
High Hairline
A high hairline starts right at the crown of the head. Both men and women with this type may seem to have a bigger forehead.
A high hairline can be fully genetic. It can also form over time as hair slowly recedes.
Straight-Lined Hairline
A straight-lined hairline doesn’t follow the head’s natural curve. Instead, it forms a straight line across the front with sharp side angles.
This shape is at times made on purpose through styling or haircuts. In other cases, a straight hairline just runs in the genes.
Bell-Shaped Hairline
Bell-shaped hairlines are also called rounded or oval hairlines. They form an upside-down U-shape, with the lowest points near the temples and the top of the bell at the center.
This shape can happen naturally in both men and women. It may also come from hair receding over time.
Triangular Hairline
A triangular hairline looks like a bell shape but is more angular than curved. It starts lower near the temples and rises to a clear point in the center.
Uneven Hairline
An uneven hairline is quite common and fully normal. One side may sit higher, or the line may look jagged or zig-zaggy.
This unevenness can run in the genes. It can also come from too much styling that pulls hair more on one side.
Cowlick
A cowlick is where a small bit of hair grows in a different direction than the hair around it. This makes a clear swirl.
Cowlicks can show up anywhere on the scalp in both men and women. They’re often found right along the hairline.
Normal vs. Receding Hairlines: What’s the Difference?
Knowing the gap between a natural hairline shape and a receding one helps you spot real changes over time.
What Makes a Hairline “Receding”
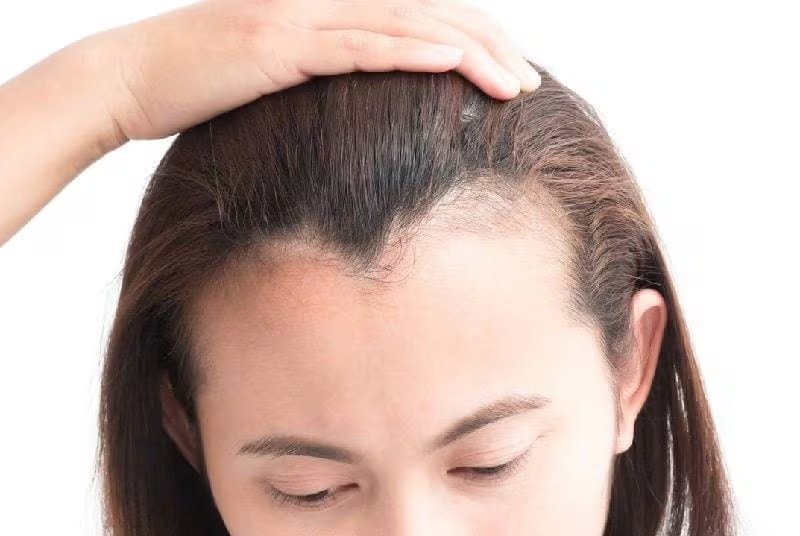
A receding hairline slowly moves back from where it started. This usually starts at the temples and grows over time.
The M-shape often forms as the middle hairline recedes unevenly. This makes the shape many people link to hair loss.
Why This Distinction Matters
Spotting early signs of recession helps you make smart choices about treatment, if you want one. Knowing your normal hairline shape makes changes easier to notice.
When Does Hair Start to Recede?
Receding hairlines are quite common, mainly in men. Knowing typical timing helps set fair hopes.
How Common Is Hair Recession?
One study found that 50% of men face balding by age 50. This makes hairline recession a widely shared thing, not a rare one.
Some people spot their hairline receding as early as the end of puberty or their early 20s. Timing shifts a lot from person to person.
A Note on Childhood Hair Loss
This is a common thing, and it’s nothing to feel shy about. Even kids as young as two may face a condition called triangular temporal alopecia, where hair falls out and leaves scabs.
Treatment Options for Hairline Concerns
If your hairline is receding, or you just don’t like how it looks, a few treatment options exist. These range from simple to surgical.
Overview of Treatment Options
| Treatment | How It Works |
| Laser hair removal or electrolysis | Raises a low hairline for a higher, sharper look |
| Low-level laser therapy | Stirs hair growth, less painful than transplants |
| Hair transplants | Lowers how the hairline looks |
| Medications (Rogaine, Finasteride) | May slow or fix hairline recession |
| Forehead reduction surgery | Lowers the hairline by removing forehead skin |
| Scalp micropigmentation | Tattoos the scalp to look like hair |
Laser Hair Removal and Electrolysis
For people with low hairlines who want a higher, sharper forehead, laser hair removal or electrolysis may help. These methods remove hair along the hairline’s edge.
Low-Level Laser Therapy
Low-level laser therapy stirs hair growth through light. This is seen as less painful than transplant surgery and thought to be safe and effective.
Hair Transplants
Hair transplants can make the hairline look a bit lower. This helps cut how big the forehead looks for those who want a lower hairline.
Medications for Receding Hairlines
Common drugs used for balding include Rogaine, Finasteride, and Propecia. Rogaine tends to work best at the center of the head, not just the hairline’s edge.
Some doctors may also talk about other drugs, like Dritho-Scalp, a psoriasis drug that may help slow hairline recession in some cases.
Forehead Reduction Surgery
Forehead reduction surgery, also called hairline surgery, is a choice-based cosmetic procedure. It lowers the hairline by removing part of the forehead while keeping hair roots intact.
Scalp Micropigmentation
Scalp micropigmentation uses a tattoo method to shade the scalp and look like hair. This result is lasting but may need touch-ups now and then.
How to Style a Receding Hairline
Styling is one of the easiest, most open ways to make a receding hairline stand out less. A few ways work well, based on your hair length and taste.
Styling Options to Consider
- Shave your head so the hairline blends with the scalp
- Pick a buzz cut to make thin spots stand out less
- Slick hair back for a clean, set look
- Grow hair longer to soften the hairline’s look
- Make a deep side part and comb hair to the side
- Grow hair longer and messier at the front to pull the eye down
- Cut straight or side-swept bangs for longer hair
Choosing the Right Style for Your Hair Type
Shorter styles, like a shaved head or buzz cut, work well if you want low upkeep. Longer styles give more room to cover or soften the hairline area.
Trying out a few styles can help you find what feels most comfy and confident. There’s no single “right” way to style a receding hairline.
Emotional and Psychological Aspects of Hairline Changes
Hairline changes can shake confidence and self-image for many people. This feeling side matters just as much as the physical fix.
Common Feelings Associated With Hairline Changes
- Feeling self-conscious about looks
- Worry about looking older
- Curiosity about treatment choices
- Unsure feelings about styling picks
Knowing these feelings are normal can ease some of the stress tied to them. Many people work through this process well with the right facts and support.
When to Talk With a Doctor
Knowing when to get expert advice helps you make smart choices about your hairline. Talking early often leads to better results.
Why Early Conversations Matter
If you’re worried about your hairline or think it’s receding, checking with a doctor before big hair loss happens is wise. In general, stopping hair loss is easier than growing back hair once it’s gone.
What a Doctor Can Offer
- Prescription medicine to help slow hair loss
- Help with stress, which can at times add to hair loss
- A personal look at your own hairline pattern
- Sending you to a specialist, if needed
A doctor can help tell apart normal hairline shape from a case that may need treatment. This clarity often brings real peace of mind.
Common Myths About Hairlines
A few wrong ideas surround hairlines and hair loss. Clearing these up helps set fair, true hopes.
Myth: There’s One “Normal” Hairline Shape
As this guide shows, hairlines come in many natural shapes and spots. No one shape is more “right” or “normal” than another.
Myth: Receding Hairlines Only Affect Men
While more common in men, women can also face patterned hair loss and hairline recession. This touches both sexes, though the pattern may look a bit different.
Myth: Nothing Can Be Done About a Receding Hairline
Many treatment choices exist, from drugs to surgery. Styling shifts also give an easy, non-medical way to manage how it looks.
Myth: Hairline Recession Always Means Significant Hair Loss
A receding hairline doesn’t always mean big overall hair loss. Patterns and how fast they move shift a lot from person to person.
Building Confidence With Your Hairline
Whether your hairline sits naturally or has shifted over time, feeling confident matters. A few mindset shifts can help support how you see yourself.
Tips for Feeling Confident
- Focus on styles that work with your hairline now
- Remember that hairline variety is fully normal
- Look into treatment if it truly matters to you
- Talk to a doctor for clear, personal facts
Confidence often comes from feeling in the know and in charge of your choices. Knowing your options, whether you use them or not, supports this feeling.
Final Thoughts on Normal Hairlines
Normal hairlines come in many shapes, including low, middle, high, bell-shaped, and more. There’s no single “right” version, and change is fully expected.
Receding hairlines, which often form a clear M-shape, are also a normal part of aging for many people. This happens to a big share of both men and women over time.
If you’re unhappy with how your hairline looks, whether receding or not, options are out there. Talking to a doctor about medicine or trying creative styling can both help you feel more sure of yourself.
Frequently asked questions
What Is Considered a Normal Hairline Shape?
There’s no single normal shape. Low, middle, high, bell-shaped, triangular, and uneven hairlines are all seen as normal.
At What Age Do Hairlines Typically Start Receding?
Some people notice it as early as their late teens or early 20s. Studies show 50% of men face balding by age 50.
Can Women Have Receding Hairlines Too?
Yes, women can face patterned hair loss and hairline recession too. It’s talked about less, but it’s still a shared thing between both sexes.
What Treatments Are Available for a Receding Hairline?
Options include drugs like Rogaine and Finasteride, hair transplants, low-level laser therapy, and forehead reduction surgery. Scalp micropigmentation is another choice.
How Can I Style a Receding Hairline?
Shaving your head, picking a buzz cut, growing hair longer, or making a deep side part can all help a receding hairline stand out less.
When Should I See a Doctor About My Hairline?
If you’re worried about recession, it’s best to see a doctor early. Stopping hair loss is usually easier than growing back hair once it’s gone.
Is an Uneven Hairline Normal?
Yes, uneven hairlines are common and normal. They can come from genes or from styling habits that pull hair more on one side.
Can Stress Cause Hairline Changes?
Yes, stress can at times add to hair loss. A doctor can help you manage stress-linked factors along with other treatments.
Leave a Reply
Daily exposure to sun, pollution, harsh styling tools, and hard water take a serious toll on your strands, leaving them dry, brittle, and prone to breakage. While salon treatments and store-bought products promise quick fixes, nothing beats the power of natural ingredients sitting right in your kitchen.
If you’re searching for an effective hair mask for damaged hair, this guide covers everything you need from understanding what damages your hair to simple DIY recipes you can whip up at home.
What Causes Hair Damage in the First Place?
Before reaching for a fix, it helps to know the root cause. According to Dr. Rinky Kapoor, a Cosmetic Dermatologist and Dermato surgeon, several everyday habits are usually to blame: hot water showers, over-shampooing, excessive heat styling, harsh sulphate and alcohol-based products, and even rough brushing techniques. Over time, these factors strip your hair of its natural moisture, leading to dryness, frizz, split ends, and breakage.
A few small changes can go a long way in preventing further damage:
- Wash your hair only every two to three days with a gentle, sulphate-free shampoo
- Detangle strands gently, starting from the ends and working upward
- Shield your hair from sun and dust with a scarf or hat when heading outdoors
- Eat a nutrient-rich diet, since healthy hair starts from within
Once you’ve got the basics covered, it’s time to bring in reinforcements of natural hair masks that repair and restore.
Best Hair Masks for Damaged Hair (By Hair Type)
For Dry Hair
Combine 5 tablespoons of gram flour (besan) and 5 tablespoons of curd with 2 tablespoons of olive oil. Apply to dry hair, leave on for 20 minutes, then wash off with shampoo followed by conditioner. The gram flour strengthens the roots, while curd and olive oil lock in moisture and shine.
For Normal Hair
Mix 2 tablespoons each of gram flour and almond powder with one egg white. Apply evenly and rinse off after 30 minutes. This blend nourishes strands and keeps them looking healthy and glossy.
For Oily Hair
Blend 2 tablespoons each of gram flour and ground fenugreek (methi) seeds into coconut milk. Massage into the scalp, leave on for an hour, then shampoo and condition as usual.
DIY Hair Masks to Repair Severely Damaged Hair
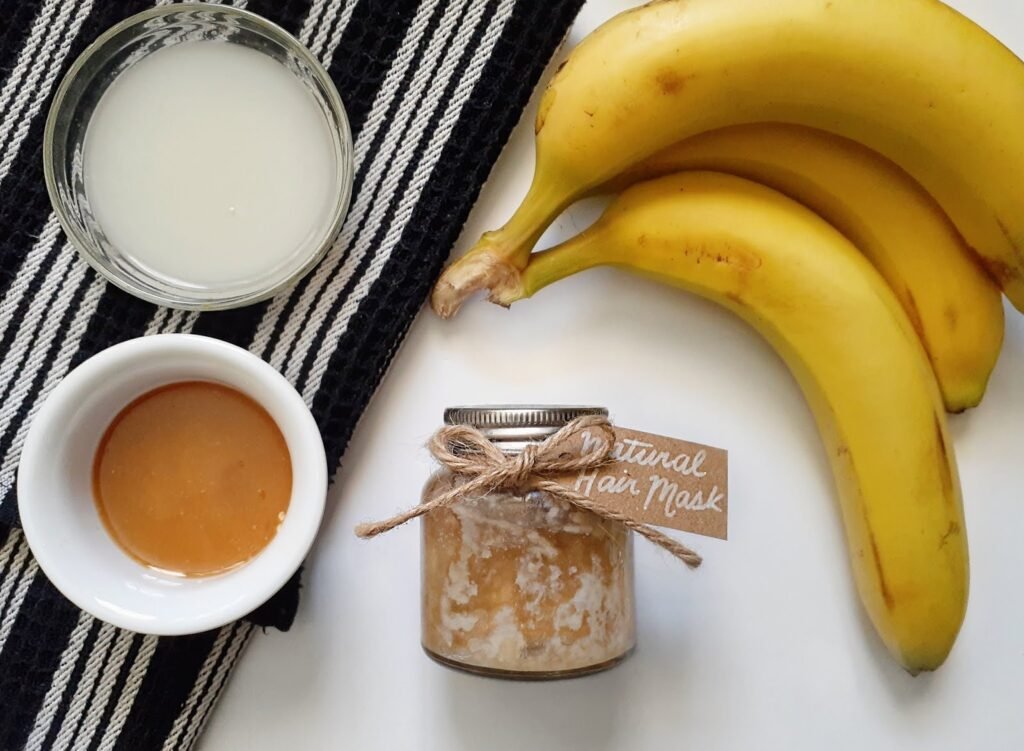
1. Banana and Coconut Oil Mask
Mash one ripe banana and blend it with 4 tablespoons of coconut oil, 1 tablespoon of glycerin, and 2 tablespoons of honey until smooth. A lump-free paste is key so it rinses out cleanly. Apply, cover with a shower cap, and wash off after 30 minutes.
2. Egg Yolk and Olive Oil Mask
Whisk three egg yolks with 3 tablespoons of olive oil, adding a few drops of your favorite essential oil. Leave on for 20 minutes before rinsing with warm (not hot) water. This protein-rich mix is ideal for restoring strength to weak, damaged strands.
3. Aloe Vera and Conditioner Mask
Mix 5 tablespoons of fresh aloe vera gel with 2 tablespoons of a silicone-free conditioner. Comb it through your hair with a wide-tooth comb for even coverage, leave on for 20 minutes, then rinse.
Hair Masks to Boost Hair Growth Naturally
Avocado and Banana Mask Mash one ripe avocado with one small banana, then stir in a tablespoon each of olive oil and wheat germ oil. Massage into roots and tips, rinse with cold water after 30 minutes, and shampoo.
Use twice weekly for best results. Avocado’s vitamin E content thickens and moisturizes hair, while banana’s potassium and natural oils guard against breakage.
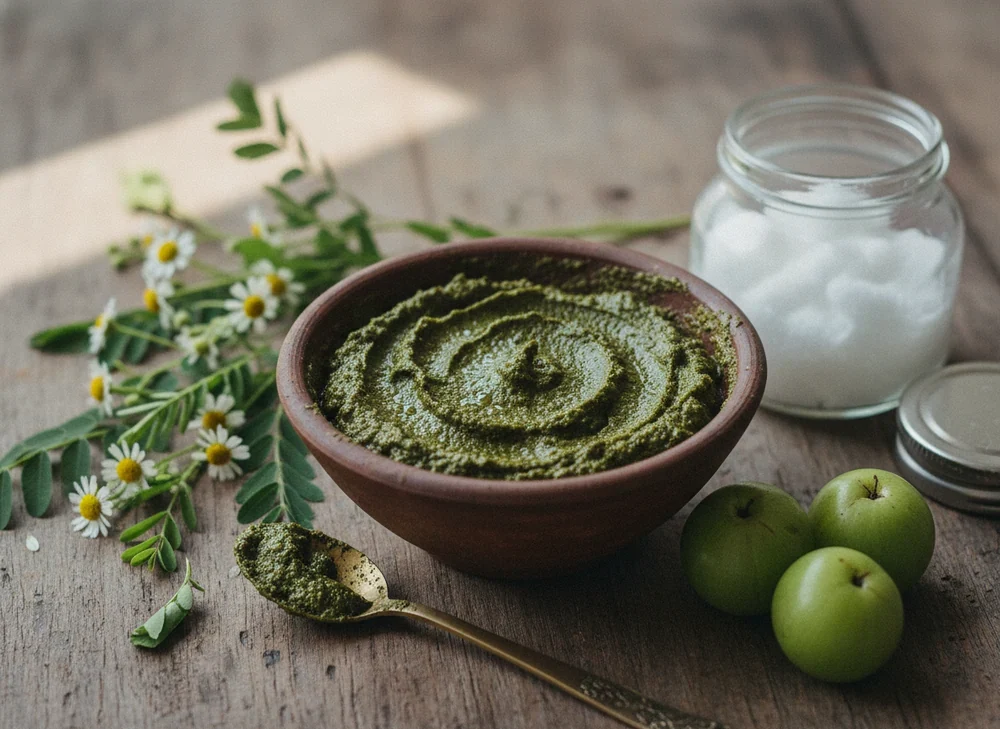
Amla, Coconut Oil, and Shikakai Mask Warm one tablespoon each of amla (gooseberry) and shikakai powder in two tablespoons of coconut oil until it just boils.
Strain, cool slightly, and massage into the scalp before bed; wash out in the morning. Amla’s vitamin C and antioxidants support a healthier scalp and stronger hair texture. Use once a week.
Flaxseed and Lemon Gel Soak a quarter cup of flaxseeds overnight. The next morning, boil them in two cups of water until thickened, then stir in the juice of half a lemon and a few drops of essential oil once cooled.
This gel-like mask can double as a natural styling gel or be left on overnight and washed out with shampoo.
Aloe Vera Masks for Every Hair Concern
Aloe vera is a beauty-cabinet staple packed with vitamins, minerals, and hydrating compounds, making it a versatile fix for multiple hair issues.
- Shine and anti dandruff: Combine 3 teaspoons aloe vera gel, 2 teaspoons yoghurt, 1 teaspoon honey, and 1 teaspoon olive oil. Massage in for 10 minutes, rest for 30 minutes, then wash.
- Deep conditioning: Mix 2 teaspoons aloe vera gel, 1 teaspoon honey, and 3 teaspoons coconut oil. Apply, leave for 30 minutes, and shampoo out.
- Anti-dandruff: Blend 1 cup aloe vera gel, 1 teaspoon honey, and 2 teaspoons apple cider vinegar. Apply generously, rest for 20 minutes, then rinse. Use it twice a month.
Coconut Oil Masks for Deep Repair
Coconut oil is one of the most trusted ingredients for damaged hair repair, thanks to its ability to penetrate the hair shaft and lock in moisture.
- Coconut and lemon: Warm coconut oil with lemon juice and honey; apply for an hour before shampooing to fight dandruff and split ends.
- Coconut and banana: Blend coconut oil with a ripe banana and a splash of coconut milk for a moisture-locking mask that also helps curb hair fall.
- Coconut and egg: Combine coconut oil with an egg and honey for a protein boost that leaves hair stronger and damage-free.
- Coconut oil mix: Blend coconut oil with almond oil, argan oil, and a tablespoon of yoghurt; leave on overnight for an ultra-soft, glossy finish.
Hibiscus Hair Masks for Strength and Shine
Hibiscus is rich in calcium and vitamin C, both of which nourish the scalp and stimulate blood circulation to support healthier hair growth.
- To reduce hair fall: Grind hibiscus petals into a paste with coconut oil, apply to the scalp, and leave for an hour before washing. Repeat weekly.
- For shine: Blend ground hibiscus flowers with almond oil and aloe vera gel; rinse after 20 minutes. Use every two weeks.
- For dandruff: Grind soaked fenugreek seeds, henna leaves, and hibiscus petals with buttermilk and lemon juice; rest for 30 minutes before washing. Use it twice a month.
- For growth: Grind 7–8 hibiscus leaves with a quarter cup of curd and 2 tablespoons of almond or coconut oil; apply generously and rinse after 15 minutes with cool water.
Quick Kitchen-Ingredient Hair Masks
Short on time? These pantry-friendly recipes come together in minutes.
| Mask | Ingredients | Benefit |
| Curd, Lemon & Honey | 1 cup curd, 1 tsp lemon juice, 1 tbsp honey | Adds shine, tames dryness |
| Mayonnaise & Egg | 1 egg white, 2 tbsp mayonnaise, 1 tsp curd | Smooths frizz, boosts protein |
| Yoghurt | Plain yoghurt applied for 20 minutes | Softens hair with lactic acid |
| Aloe Vera & Honey | Equal parts gel and honey | Conditions and hydrates |
| Sugar Water | 1 tsp sugar in 1 cup water | Controls frizz naturally |
How to Get the Best Results From a Hair Mask
- Apply to damp, not soaking wet hair so the mask isn’t diluted.
- Focus on damaged areas usually mid-lengths and ends rather than the scalp, unless the recipe specifically targets scalp health.
- Use a shower cap to trap heat and help the mask penetrate better.
- Stick to a routine most homemade masks work best when used consistently, once or twice a week.
- Always patch test new ingredients, especially essential oils or lemon juice, to rule out irritation.
Final Thoughts
You don’t need an expensive salon treatment to bring damaged hair back to life. With ingredients like coconut oil, aloe vera, banana, and hibiscus already in your kitchen, you can create an effective hair mask for damaged hair that repairs, strengthens, and restores shine naturally and affordably. Pick the recipe that matches your hair’s needs, stay consistent, and you’ll start noticing healthier, more manageable hair within a few weeks.
Frequently Asked Questions
How do you repair hair damaged by straightening or heat styling?
A protein-rich mask works best here. Whisk three egg yolks with three tablespoons of olive oil and a few drops of essential oil, apply for 20 minutes, and rinse with warm water.
How can you fix hair breakage naturally?
A hibiscus and coconut oil mask is a great starting point. Hibiscus strengthens the hair shaft while coconut oil restores moisture — apply weekly for noticeable results.
What’s a good home remedy for split ends?
Ground hibiscus flowers mixed with almond oil and aloe vera gel help soothe the scalp and smooth split ends when used weekly.
Does hair colouring damage your hair?
It depends on the type of colour used. Permanent colour opens the hair cuticle to deposit pigment, which can weaken the strand over time. Semi or demi permanent colours are gentler and add shine without lasting structural damage.
Leave a Reply
Attraction feels mysterious, but it follows real patterns and habits. Small things pull people closer or push them away fast. This guide explains what actually creates connection or distance.
You will learn the biggest turn ons people report. You will also learn the biggest turn offs to avoid. By the end, you will understand why attraction shifts over time.
Use up and down arrow keys to resize the meta box pane.
What Are Turn Ons and Turn Offs?
Turn ons and turn offs shape how attraction builds or fades. They influence first impressions and long-term relationship satisfaction alike. Understanding both helps you build stronger, healthier connections.
Meaning of Turn Ons in a Relationship
A turn on is any trait that increases attraction toward someone. This includes behaviors, habits, and even small gestures. Turn ons vary widely from person to person naturally.
Common turn ons include kindness, confidence, and genuine emotional openness. These qualities signal safety and compatibility to a potential partner.
Meaning of Turn Offs in a Relationship
A turn off is a behavior or trait that reduces attraction. These moments often come as sudden, unexpected surprises. Sometimes they build slowly through repeated frustrating patterns.
Turn offs can range from minor annoyances to serious dealbreakers. Poor hygiene, dishonesty, and rudeness are frequently mentioned examples.
Common Turn Ons in Relationships
Certain qualities consistently attract people across different relationships and dating stages. These turn ons build trust and deepen emotional intimacy over time.
Emotional Connection and Vulnerability
Emotional openness creates powerful bonds between romantic partners quickly. When someone shares feelings honestly, it builds real trust. This vulnerability, though scary, is deeply attractive to most people.
People feel safer with partners who express emotions clearly. This safety encourages deeper intimacy and long-term relationship satisfaction.
Verbal Communication and Honesty
Clear communication ranks among the most attractive relationship qualities. Saying what you want removes guesswork and confusion. Honest compliments also make partners feel genuinely appreciated.
| Communication Habit | Why It Attracts |
| Direct honesty | Builds trust quickly |
| Active listening | Shows genuine interest |
| Sincere compliments | Makes partner feel valued |
| Clear boundaries | Reduces future conflict |
Initiative and Thoughtfulness
Taking initiative shows genuine interest and relationship investment. Planning dates or offering help without being asked matters greatly. These small gestures prove someone is truly paying attention.
Thoughtful actions often speak louder than words ever could. Partners notice and appreciate this effort immediately.
Common Turn Offs in Relationships
Just as certain traits attract, others consistently repel potential partners. Recognizing these patterns helps you avoid damaging your own relationships.
Poor Communication and Dishonesty
Weak communication erodes trust faster than almost anything else. Without honest dialogue, partners struggle to understand each other’s needs. This gap often leads to resentment and eventual disconnection.
Dishonesty compounds this problem significantly over time. Once trust breaks, rebuilding it takes considerable effort and patience.
Selfishness and Lack of Consideration
Constantly prioritizing your own needs damages relationship balance. Partners want to feel considered and valued equally. Ignoring someone’s opinions or feelings signals deeper selfishness problems.
Self-care matters, but it shouldn’t come at your partner’s expense. Balance between independence and consideration keeps relationships healthy.
Inconsistency and Unreliability
Unpredictable behavior makes partners feel anxious and unsure. Consistency builds the foundation for lasting trust and security. When someone frequently changes plans, it signals unreliability.
Small broken promises accumulate into bigger relationship problems. Partners begin questioning whether they can depend on you.
Disrespect and Rudeness
Disrespectful behavior toward anyone reflects poorly on character. Rudeness toward waitstaff or strangers reveals deeper personality traits. This behavior often predicts how someone treats you eventually too.
Common disrespectful turn offs include:
- Being overly critical or picking apart small mistakes
- Refusing to compromise on plans or decisions
- Speaking rudely to service workers or strangers
- Dismissing a partner’s feelings or opinions
- Showing a cocky or arrogant attitude
Turn Ons and Turn Offs for Men
While attraction is personal, certain patterns appear frequently among men. These generalizations don’t apply universally, but they offer useful insight.
What Men Commonly Find Attractive
Men often cite emotional connection as a major attraction factor. Genuine interest and engaged listening rank highly too. Confidence without arrogance also appeals strongly to most men.
Physical presentation matters, but personality often carries more weight. Authenticity tends to outperform performative behavior consistently.
What Men Commonly Find Unattractive
Excessive negativity or constant criticism often pushes men away. Dishonesty and manipulation rank as serious dealbreakers too. Lack of independence can also feel unattractive over time.
Neediness sometimes signals deeper attachment insecurities beneath the surface. Working through these patterns can improve relationship dynamics significantly.
Turn Ons and Turn Offs for Women
Women’s preferences also follow certain recognizable patterns in dating research. These trends provide helpful, general guidance for building attraction.
What Women Commonly Find Attractive
Attentiveness ranks extremely high on most women’s attraction lists. Reducing phone distractions during dates shows genuine presence and respect. Sensitivity to emotional needs matters deeply as well.
Style and self-care also contribute to overall attraction levels. Small details, like clean shoes, sometimes leave lasting impressions.
What Women Commonly Find Unattractive
Arrogance and excessive self-praise often create immediate distance. Selfishness ranks as another commonly cited relationship turn off. Lack of attention during dates frustrates many women too.
| Turn Off | Impact on Attraction |
| Cocky attitude | Signals self-centeredness |
| Constant phone use | Feels disrespectful |
| Selfish behavior | Reduces emotional safety |
| Poor personal grooming | Lowers physical attraction |
Why Turn Ons and Turn Offs Change Over Time
Attraction isn’t fixed; it shifts as relationships evolve naturally. Understanding this helps normalize changing feelings within long-term partnerships.
How Comfort Can Shift Attraction
Early relationship excitement often fades into comfortable familiarity eventually. Habits that once seemed charming can start feeling irritating. This shift doesn’t mean the relationship is failing.
Comfort sometimes breeds complacency if left unaddressed for too long. Actively maintaining effort helps preserve original attraction levels.
The Role of Attachment Style
Your attachment style influences which behaviors you find attractive. Avoidant tendencies might make emotional closeness feel overwhelming initially. Recognizing these patterns helps you grow toward healthier connections.
What feels like a turn off might reflect your own patterns. Self-awareness often transforms perceived dealbreakers into growth opportunities.
How to Handle Turn Offs in a Relationship
Discovering a turn off doesn’t automatically mean ending things. How you respond matters more than the turn off itself.
Communicating Concerns Constructively
Open communication resolves most relationship turn offs effectively. Start by identifying exactly what bothers you specifically. Then express this concern using loving, non-judgmental language.
Avoid blame-focused statements that trigger defensiveness in partners. Instead, focus on how specific behaviors make you feel.
Knowing When It’s a Dealbreaker
Some turn offs represent minor, fixable annoyances between partners. Others reveal fundamental incompatibilities worth taking seriously. Distinguishing between these categories protects your long-term happiness.
Ask yourself these questions when evaluating a turn off:
- Is this behavior a pattern or a one-time mistake?
- Does this conflict with your core values?
- Can open communication realistically resolve this issue?
- Would ignoring this repeatedly harm your wellbeing?
Frequently Asked Questions
What is the biggest turn on in a relationship?
Emotional connection consistently ranks as the top turn on. Feeling genuinely understood creates powerful, lasting attraction between partners.
What is the biggest turn off in a relationship?
Poor communication and dishonesty rank among the biggest turn offs. Both behaviors quickly erode trust and emotional safety.
Can turn offs change over time?
Yes, attraction naturally shifts as relationships develop and mature. Comfort sometimes changes how you perceive certain behaviors.
Should every turn off end a relationship?
No, many turn offs are fixable through honest, constructive communication. Reserve serious action for repeated patterns or core value conflicts.
Are turn ons and turn offs the same for everyone?
No, preferences vary significantly based on individual values and experiences. What attracts one person may repel another completely.
Leave a Reply
Money decisions shape your future in ways that matter deeply. Choosing between different advisors can feel overwhelming and confusing. This guide breaks down everything you need to know about independent financial advice.
You will learn what makes advice truly independent. You will also learn how to find a trustworthy advisor. By the end, you will know exactly what to look for.
What Is Independent Financial Advice?
Independent financial advice means guidance that isn’t tied to one company. An independent financial advisor works across the whole market. They recommend products from many different providers, not just one.
This independence matters because it removes bias from recommendations. A tied advisor can only suggest their employer’s products. An independent adviser has no such restriction.
The result is advice built around your needs, not sales targets.
How It Differs from Restricted Financial Advice
Restricted advice comes with limits on what can be recommended. A restricted adviser might only sell one company’s products. They might also specialize in a single financial area, like pensions.
Independent advice has no such boundaries. The adviser searches the entire market for you. This means better matches for your specific financial situation.
| Feature | Independent Advice | Restricted Advice |
| Product range | Whole of market | Limited to specific providers |
| Bias risk | Low | Higher |
| Specialization | Broad coverage | Often narrow (e.g., pensions only) |
| Regulation | FCA-regulated | FCA-regulated |
The Meaning and Origin of Independent Financial Adviser
The term IFA originated in the United Kingdom back in 1988. Regulators introduced a rule called polarisation at that time. Advisers had to choose one of two paths.
They could either work for a single provider or operate independently. This split created the modern IFA category we know today.
Other countries later adopted similar independent advisor models. Hong Kong and Australia both use comparable regulatory frameworks now.
Who Can Benefit from Independent Financial Advice?
Almost anyone managing money can benefit from unbiased guidance. Some situations, however, make independent advice especially valuable. Let’s look at the main groups.
People Planning for Retirement or Pensions
Retirement planning involves complex decisions about pensions and savings. An independent advisor can compare pension products across every provider. This comparison often reveals better rates and terms.
Pension transfers, in particular, need careful, unbiased analysis. Getting this wrong can cost you thousands of pounds. Independent advice protects against costly mistakes here.
People Managing Savings, Investments, or Assets
Investors with multiple accounts often need a coordinated strategy. An independent adviser looks at your full financial picture. They then build a plan matching your actual goals.
This holistic approach beats piecemeal advice from separate providers. Your savings, investments, and assets work together, not in isolation.
People Funding Long-Term Care or Home Adaptations
Care costs can quickly drain savings without proper planning. Independent advisers help families navigate these difficult financial decisions. They explain payment options clearly and objectively.
Common care-funding topics include:
- Paying for home adaptations or extensions
- Funding long-term residential or nursing home care
- Managing income and savings while already in care
- Understanding deferred payment agreements
Attorneys Managing Someone Else’s Financial Affairs
Attorneys acting under power of attorney carry serious responsibility. They must make sound financial decisions for someone else. Independent advice offers extra reassurance during this process.
An unbiased adviser explains options without pushing specific products. This protects both the attorney and the person they represent.
Independent vs Restricted Financial Advisers
Understanding this distinction helps you choose the right professional. The difference affects both cost and the quality of recommendations you receive.
What Makes an Adviser “Independent”
Independent advisers meet strict regulatory standards for market coverage. They must consider products from across the entire industry. No single provider can influence their recommendations.
This structure creates natural alignment with your interests. The adviser earns trust by finding what truly works for you.
What Makes an Adviser “Restricted”
Restricted advisers operate within defined boundaries set by their employer. Some restrictions focus on product type, like pensions or investments. Others limit advisers to a small panel of providers.
Restriction isn’t always negative, though it requires more scrutiny. A specialist restricted adviser can still offer excellent, focused expertise.
Why Independent Advice Often Covers a Wider Range of Products
Whole-of-market access means more options for comparison. Independent advisers can weigh dozens of providers against each other. This wider net often surfaces better-suited financial products.
More choice generally leads to more competitive rates too. Providers know independent advisers will compare their offerings against rivals.
Benefits of Choosing an Independent Financial Advisor
Independent advice offers several clear advantages over other options. These benefits explain why many people prefer this route.
Unbiased, Whole of Market Recommendations
Independent advisors have no incentive to favor one company. Their recommendations come purely from matching products to your needs. This objectivity is the core value of independent advice.
You get honest assessments of every option available to you. Nothing gets hidden or downplayed to protect a sales quota.
Advice Tailored to Your Personal Goals
Generic financial products rarely fit everyone’s circumstances perfectly. Independent advisers build strategies around your specific life situation. Your goals, timeline, and risk tolerance all shape their advice.
This personalized approach often produces better long-term outcomes. Cookie-cutter plans simply can’t match this level of customization.
No Ties to a Specific Bank, Insurer, or Investment Firm
Freedom from corporate ties changes how advice gets delivered. There’s no pressure to hit internal sales targets. There’s no pull toward one company’s in-house products.
This structural independence is what separates true IFAs from salespeople. It’s the foundation of trustworthy financial guidance.
What to Consider Before Choosing an Adviser
Not every independent advisor suits every client equally well. A few key factors deserve careful attention before you commit.
Checking Qualifications and Regulatory Status
Every legitimate adviser needs proper qualifications and registration. Look for Level 4 or above on the national framework. A Statement of Professional Standing (SPS) is also essential.
Specialized areas require additional credentials too. Long-term care planning, for example, often needs a CF8 or CeLTCI qualification.
Understanding Advisor Fees and Costs
Fee structures vary significantly between different advisers. Some charge flat fees, while others take a percentage. Always ask for a clear breakdown before signing anything.
Key questions to ask about costs include:
- What is the total cost for the service?
- Is this a one-time fee or ongoing charge?
- Are there hidden costs in recommended products?
- How does payment structure affect their recommendations?
Confirming Whether Advice Is Independent or Restricted
Advisers must clearly disclose their status at your first meeting. Ask directly whether their advice is independent or restricted. They should explain any restrictions in plain language.
If this explanation feels vague or evasive, consider it a warning sign. Transparency here reflects transparency in their overall approach.
How to Find a Qualified Independent Financial Adviser
Finding the right adviser takes some research, but it’s worth the effort. Several reliable paths exist for locating trustworthy professionals.
Checking Financial Conduct Authority (FCA) Registration
The FCA regulates all financial advisers in the UK. Their public register lets you verify any adviser’s credentials instantly. Always confirm registration before engaging any advisor’s services.
This simple check protects you from unregulated or fraudulent operators. It takes just a few minutes online.
Using Trusted Resources Like MoneyHelper or Citizens Advice
Free, impartial organizations offer excellent starting points for research. MoneyHelper provides guidance on choosing advisers and understanding fees. Citizens Advice offers similar support for financial decisions.
These resources help you understand your options before meeting advisers. They also explain the difference between guidance and formal advice.
Questions to Ask Before Hiring an Adviser
A good first meeting should clarify several important points. Come prepared with specific questions for the adviser.
Consider asking:
- Are you independent or restricted, and how so?
- What are your qualifications and areas of expertise?
- How do you charge for your services?
- Can you provide references from existing clients?
- What happens if I’m unhappy with your advice?
Frequently Asked Questions
Is independent financial advice always better than restricted advice?
Not necessarily. Independent advice offers broader options, but a specialist restricted adviser can still deliver excellent, focused expertise for narrow needs.
How much does independent financial advice cost?
Costs vary by adviser and service complexity. Always request a clear fee breakdown before committing to any arrangement.
Do I need independent financial advice for retirement planning?
It’s highly recommended, especially for pension transfers. Unbiased comparison across providers often reveals better retirement outcomes.
How do I verify an adviser is genuinely independent?
Ask them directly and check their FCA registration. Genuine independent advisers will explain their status clearly and confidently.
Can independent advisers help with long term care costs?
Yes, many specialize in care funding. Look for advisers with CF8 or CeLTCI qualifications for this specific area.
Leave a Reply
Rice flour has been used in home skincare for generations, especially across parts of Asia where it’s valued for its mild texture and gentle effect on the skin. It’s simply rice that’s been ground into a fine powder, and despite how basic that sounds, it carries a surprising number of benefits for the face. It’s inexpensive, easy to find, and works well for several skin types when used the right way.
This guide covers everything you need to know why rice flour works, its key benefits, how to use it, DIY recipes you can try at home, and precautions to keep in mind.
Why Rice Flour Is Good for Skin
Rice flour has a few natural properties that make it useful in skincare:
- Mild exfoliation Its fine, slightly grainy texture helps lift away dead skin cells without scratching or irritating the skin.
- Oil absorption It soaks up excess surface oil, which makes it especially handy for oily and combination skin.
- Brightening effect Regular use can help even out skin tone and reduce a dull, tired appearance.
- Calming properties It tends to be gentle and soothing, which helps with mild redness or irritation.
- Cleansing action It can help lift dirt and impurities sitting on the skin’s surface.
- Antioxidant content Rice contains compounds that help protect skin cells from everyday environmental stress.
Because of this mix of properties, rice flour is considered a fairly all-purpose ingredient rather than something suited to just one skin concern.
Key Benefits of Rice Flour for Face
1. Brighter, more even-looking skin
Regular gentle exfoliation removes the buildup of dead skin and grime that makes skin look flat or dull. Over time, this can leave the complexion looking fresher and more even.
2. Controls oiliness
Rice flour absorbs excess sebum, which helps reduce that greasy shine that builds up through the day, particularly useful for people with oily or acne-prone skin.
3. Soothes irritated skin
It has a naturally calming quality, which can help ease minor redness or sensitivity, making it gentler than many chemical exfoliants.
4. Helps minimize the look of pores
By clearing away trapped dirt and oil, rice flour can make pores appear less noticeable over time.
5. Supports smoother texture
Consistent use helps soften rough patches, leaving skin feeling smoother to the touch.
6. May help delay early signs of aging
The antioxidants in rice can help protect skin from oxidative stress, one of the contributing factors to premature aging.
Common Uses of Rice Flour for Face
Rice flour isn’t limited to a single use. It’s commonly used as:
- A gentle face scrub or exfoliant
- A base for hydrating or brightening face masks
- A natural substitute for talc-based powders
- An ingredient in homemade cleansers
- A soothing pack for sunburned or irritated skin
DIY Rice Flour Recipes for Face
Here are a few simple combinations you can try at home. Always patch-test on your inner arm first and wait 24 hours to check for any reaction.
Basic Brightening Mask
Mix rice flour with plain yogurt or milk to form a smooth paste. Apply to clean skin, leave on for 15–20 minutes, then rinse with lukewarm water.
Oil-Control Pack (for oily skin)
Combine rice flour with a small amount of rose water to make a paste. This helps soak up excess oil while keeping the mixture light.
Soothing Honey Mask (for dry or sensitive skin)
Mix rice flour with a little raw honey and a few drops of water. Honey adds moisture, balancing out rice flour’s oil-absorbing nature.
Gentle Scrub
Mix rice flour with a small amount of coconut or olive oil and gently massage onto damp skin in circular motions for 1–2 minutes before rinsing off.
Turmeric Glow Pack
Add a pinch of turmeric to rice flour and mix with milk or water. This combination is often used for its brightening and calming effect, though turmeric can temporarily stain lighter skin tones.
How to Apply a Rice Flour Face Pack
- Start with a clean, makeup-free face.
- Mix the rice flour with your chosen liquid ingredient until it forms a smooth, spreadable paste not too runny, not too thick.
- Apply evenly across the face, avoiding the eye area.
- Leave it on for 15–20 minutes, or until it starts to feel slightly dry.
- Rinse off with lukewarm water using gentle circular motions if you want a mild scrub effect.
- Pat the skin dry and follow up with a moisturizer.
How Often to Use Rice Flour on Face
For most skin types, using a rice flour face pack 2-3 times a week is enough to see benefits without overdoing the exfoliation. Sensitive skin may do better with just once or twice a week. Overuse can lead to dryness or irritation, so it’s best not to use it daily.
Possible Side Effects of Rice Flour on Skin
While rice flour is generally gentle, it isn’t completely risk-free for everyone:
- Some people may experience mild dryness, especially with frequent use.
- Those with a sensitivity or allergy to rice may notice redness, itching, or irritation.
- Overly vigorous scrubbing can cause micro-tears or irritation on sensitive skin.
- Combining it with irritating ingredients (like undiluted lemon juice) can sometimes cause more harm than good.
A patch test before full use is always a good idea, especially if you have reactive or sensitive skin.
Who Should Avoid Rice Flour Face Packs
- People with a known rice allergy
- Those with active eczema, broken skin, or open wounds on the face
- Anyone currently using strong exfoliating treatments (like retinoids or chemical peels), since combining exfoliants can over-strip the skin
If you have a chronic skin condition, it’s a good idea to check with a dermatologist before adding any new ingredient to your routine.
Tips for Best Results
- Always use a clean bowl and fresh ingredients when preparing your mask.
- Avoid applying near the eyes and lips.
- Don’t leave masks on until they’re fully dry and tight, as this can dehydrate the skin.
- Moisturize after every use to maintain skin balance.
- Store any leftover paste in the fridge for no more than a day, and avoid using it if it smells off.
Conclusion
Rice flour is a simple, affordable, and largely gentle ingredient that can genuinely support healthier-looking skin when used consistently and correctly. Whether your goal is to control oil, brighten dull skin, or simply add a natural step to your routine, it’s worth trying just remember to patch test first and pay attention to how your skin responds.
Frequently Asked Questions
Is rice flour good for all skin types?
It generally suits most skin types, though those with very dry or sensitive skin should use it less frequently and pair it with hydrating ingredients.
Can rice flour lighten skin?
It won’t change your natural skin tone, but regular use may help even out dullness and improve overall radiance.
Can I use rice flour daily?
It’s better used 2–3 times a week rather than daily, to avoid over-exfoliating the skin.
Is homemade rice flour as effective as store-bought?
Yes, as long as it’s finely ground and free from additives, homemade rice flour works just as well for DIY skincare.